KEY POINTS
- Magna approves Levack mine restart in Canada.
- Commercial production targets mid-2028.
- Projected after-tax returns reach 92.4%.
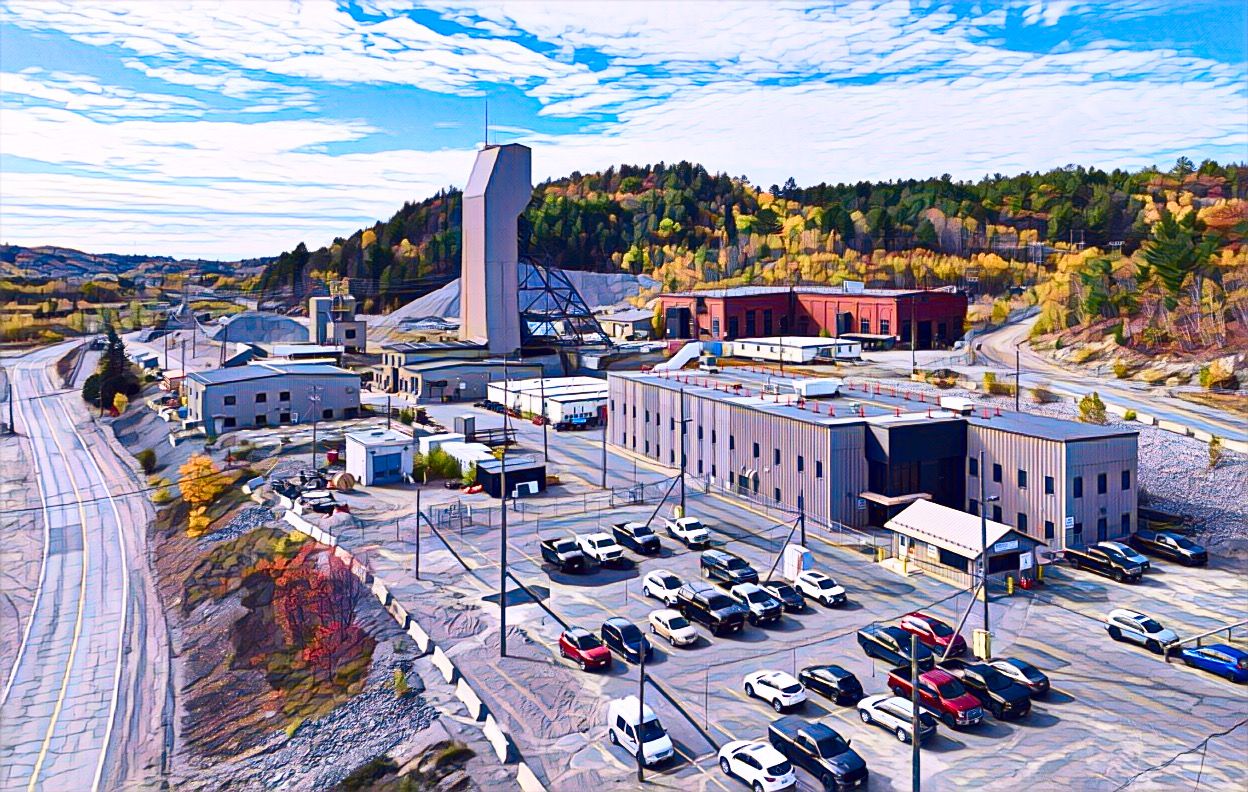
Canadian mining company Magna Mining has approved plans to restart its fully permitted Levack copper mine in the Sudbury Basin of northeastern Ontario, Canada, following positive results from a preliminary economic assessment (PEA).
The decision moves the project closer to commercial production, which is expected to begin in mid-2028. Magna believes the mine can deliver strong financial returns while requiring relatively limited additional investment because of previous capital expenditure and existing infrastructure.
Magna Mining CEO Jason Jessup said the assessment demonstrated the mine’s potential to operate as a low-capital-cost project with an attractive internal rate of return (IRR) and a clear path towards commercial production.
The company plans to prioritise higher-grade copper and precious metal footwall zones during the early stages of mining. According to Jessup, this strategy is expected to generate revenue before full commercial production and strengthen the project’s financial performance.
Initial funding requirement put at C$8.6 million
Magna estimates that initial capital expenditure from January 1, 2027, until the start of commercial production will amount to C$70.1 million, taking into account the timing of equipment financing.
However, the company expects to offset much of this expenditure through refundable tax credits and operating cash flow generated before commercial production begins.
The assessment estimates that refundable tax credits will contribute approximately C$5.6 million, while pre-commercial production operating cash flow could reach C$55.9 million under the base-case commodity price assumptions.
After accounting for these sources of funding, the project’s net initial funding requirement is estimated at C$8.6 million.
The relatively low funding requirement reflects the substantial investment already made in the mine and the availability of existing infrastructure, which reduces the need for additional spending on development facilities and other essential assets.
The preliminary economic assessment estimates a payback period of 0.6 years, alongside an after-tax internal rate of return of 92.4% and an after-tax net present value (NPV) of C$227 million under the base-case scenario.
The company also examined how the project would perform using average commodity prices recorded in September 2026.
Under that pricing scenario, the mine’s estimated after-tax NPV increases to C$313.6 million, while the projected after-tax IRR rises to 115.8%.